Your money life can feel disorganized even when nothing is dramatically wrong.
There is the subscription you keep meaning to cancel. The credit card balance you know approximately but not exactly. The annual payment you vaguely remember is coming soon. The savings transfer you intended to set up three months ago. The small financial tasks that are individually manageable but somehow become one large cloud of I really need to deal with that.
You do not need to spend your entire weekend fixing it.
Give yourself one Saturday afternoon.
The goal of this weekend financial reset is not to create the world’s most detailed budget, optimize every financial decision, or emerge four hours later as a completely different person with money.
It is much more practical:
Know where things stand. Deal with what is quietly costing you. Prepare for what is coming next. Put a few useful systems in place. Then close the laptop.
Disclosure: As an Amazon Associate, After Friday earns from qualifying purchases. If you buy through an eligible link, we may earn a commission at no extra cost to you.
Want to do the reset as you read?
Download the free Saturday Money Reset Printable and use it to keep your balances, upcoming expenses, recurring charges, next actions, and monthly follow-up all in one place.
It’s designed to follow this reset step by step, so you can work through the afternoon without building your own spreadsheet or trying to remember what comes next.
[DOWNLOAD THE FREE MONEY RESET PRINTABLE]
Before You Start: Give the Afternoon a Finish Line
Do not begin by downloading three budgeting apps.
Start with what you already have.
You need:
- access to your bank and credit card accounts
- your calendar
- somewhere to write things down
- recent statements if your banking app does not make older transactions easy to review
- roughly two and a half to three hours without trying to solve every financial question you have ever had
Use a notebook, a spreadsheet, or a blank document. The tool matters much less than keeping everything in one place.
Shop the Undated Budget Planner →
Then make yourself one rule:
If something needs research, a phone call, or a bigger decision, write down the next action instead of disappearing into it for 45 minutes.
Today is about getting the whole system visible.
Not getting trapped inside one problem.
1:00 PM — Make a One-Page Money Snapshot
Start with facts.
Not goals. Zero guilt. Not what you think you should be spending.
Write down what is true today.
Include:
Money available
Note the current balances of the checking and savings accounts you actually use.
You do not need to include every investment account or calculate your complete net worth unless that information is useful to you today.
The purpose is to answer a much simpler question:
What money is currently available, and where is it?
Money already spoken for
Next, write down:
- current credit card balances
- minimum debt payments due soon
- major bills still due this month
- any known payment coming before your next paycheck
- larger irregular expenses you know are approaching
Think insurance renewal, car maintenance, a trip, a birthday, school costs, an annual membership, or anything else that will not appear neatly under “monthly bills.”
Money coming in
Add your next expected payday or other reliable income dates.
That is enough for the first pass.
You are not building a financial statement.
You are creating a usable map.
1:25 PM — Review the Last Month for Patterns, Not Mistakes
Now open your most recent month of transactions.
If your spending varies significantly from month to month, look back a little farther. You are trying to see what is normal enough to plan around, not perform a forensic investigation into every coffee.
Use broad categories.
For example:
- fixed bills
- groceries and household essentials
- transportation
- eating out
- shopping and entertainment
- subscriptions and recurring charges
- savings or debt payments
- unusual one-time expenses
Then look for only three things.
1. Something that cost more than you thought
Maybe eating out was higher than it felt.
Perhaps your grocery total surprised you.
Or a “small” shopping category has quietly become a regular one.
You do not have to immediately cut it.
Knowing the real number is already useful.
2. Something that keeps repeating
A recurring charge.
A weekly habit.
A fee.
A purchase pattern that happens often enough to deserve its own place in your plan.
3. Something you could realistically change
Not ten things.
One.
The most useful financial reset is rarely the one with the longest list of restrictions.
It is the one that changes something you will still be doing next month.
1:55 PM — Do the Subscription and Recurring-Charge Sweep
This is usually the fastest place to find money that is leaving without much active decision-making.
Go through your checking account and credit card transactions and look specifically for recurring charges.
Include obvious subscriptions, but also check:
- app subscriptions
- memberships
- software
- cloud storage
- recurring donations
- delivery memberships
- annual services that may renew soon
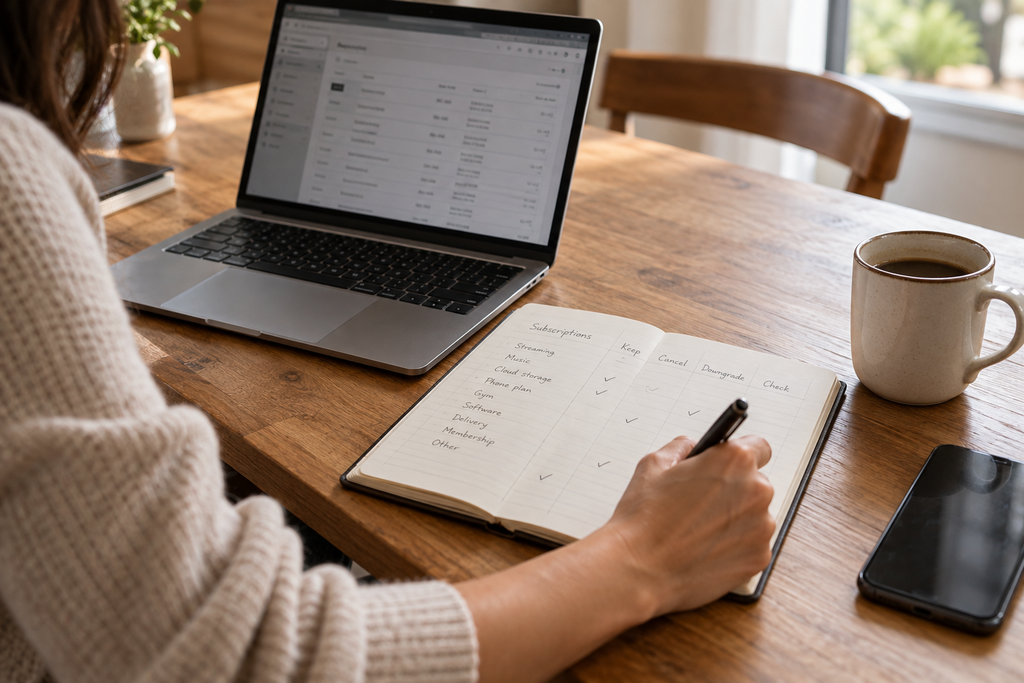
For each one, choose one of four labels:
Keep. Cancel. Downgrade. Check.
“Check” is for the subscription you cannot make a decision about in 30 seconds.
Maybe you share it with someone.
Or you need to know the cancellation date.
The annual renewal is already paid?
Do not let one confusing account derail the reset. Write down what you need to find out and keep moving.
If you cancel something, save the confirmation and watch the next statement to make sure the recurring charge actually stops. The FTC specifically recommends keeping cancellation records and monitoring later statements when ending recurring subscriptions.

2:20 PM — Put the Next 30 Days on One Page
A budget tells you how you intend to use your money.
A calendar tells you when real life is going to ask for it.
You need both perspectives.
Open your calendar and look at the next 30 days.
Write down:
- paydays
- rent or mortgage
- utilities
- credit card due dates
- loan payments
- insurance
- memberships or annual renewals
- appointments that will cost money
- birthdays or gifts
- travel
- car expenses
- planned events
- any other expense you already know is coming
This is also the moment to notice expenses that are predictable but not monthly.
An annual insurance bill is not an emergency simply because it does not happen every month.
Neither is a car registration, holiday gift budget, or yearly software renewal.
Once something has a date and an estimated cost, it becomes much easier to prepare for.
Choose one adjustment for the month ahead
Look at your transaction review and your calendar together.
Then make one practical adjustment.
Maybe you give eating out a slightly smaller limit because a birthday dinner is already on the calendar.
Or you leave more room for groceries because last month’s target was obviously unrealistic.
You create a small amount for car maintenance instead of hoping next month’s service somehow disappears?
Do not build an aspirational budget for a version of your life that does not exist.
Use the life you actually have.
2:50 PM — Fix One or Two Systems
This is where the afternoon starts paying you back later.
Choose one or two, not six.
Automate a savings transfer
If your income and cash flow are predictable enough, consider setting a small recurring transfer shortly after payday.
The amount should be realistic.
A transfer you leave running for six months is more useful than an ambitious one you cancel next week.
Automatic transfers can help make saving more consistent, but you still need enough money left in checking to cover upcoming transactions. The CFPB specifically advises monitoring balances when using automatic transfers or payments to avoid overdraft or insufficient-funds problems.
Make one bill harder to forget
That might mean:
- turning on a payment reminder
- adding the due date to your calendar
- setting up bill pay
- using autopay for a predictable bill
- moving the reminder several days earlier so you have time to act
Again, do not automate something blindly.
Know the amount, know the date, and know which account will fund it.
Give irregular expenses somewhere to go
If you already know that a $300 annual expense is coming, start setting aside part of it before the bill arrives.
It does not need a complicated spreadsheet.
Even a separate savings category or account nickname can make the money easier to distinguish from everyday spending.
Make one decision you have been postponing
Maybe you have been meaning to increase a savings contribution.
Or you need to stop paying for a service.
Maybe one credit card has been carrying a balance and you need to decide what you can realistically pay above the minimum this month.
Or the next step is simply calling a provider on Monday.
The goal is not to solve every financial priority during this block.
It is to stop leaving all of them undefined.
3:20 PM — Clear the Financial Admin Pile
Money organization is not only numbers.
It is also knowing where the paperwork went.
Take 20 to 25 minutes and deal with the financial admin that tends to float between your inbox, downloads folder, kitchen counter, and the place where “important papers” go to disappear.
Keep the categories broad.
For example:
- taxes
- insurance
- banking
- debt or loans
- vehicle
- home
- medical
- employment
- warranties or major purchases
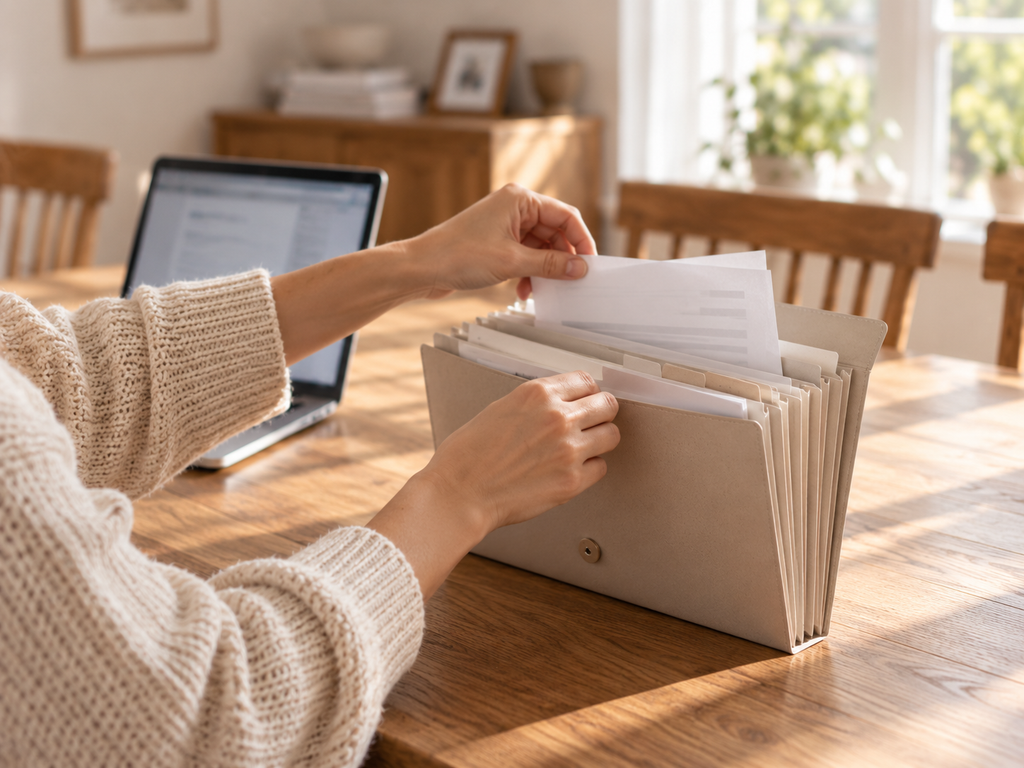
Create a straightforward digital folder structure or put important paper records together.
Do not store banking passwords inside an ordinary document or spreadsheet.
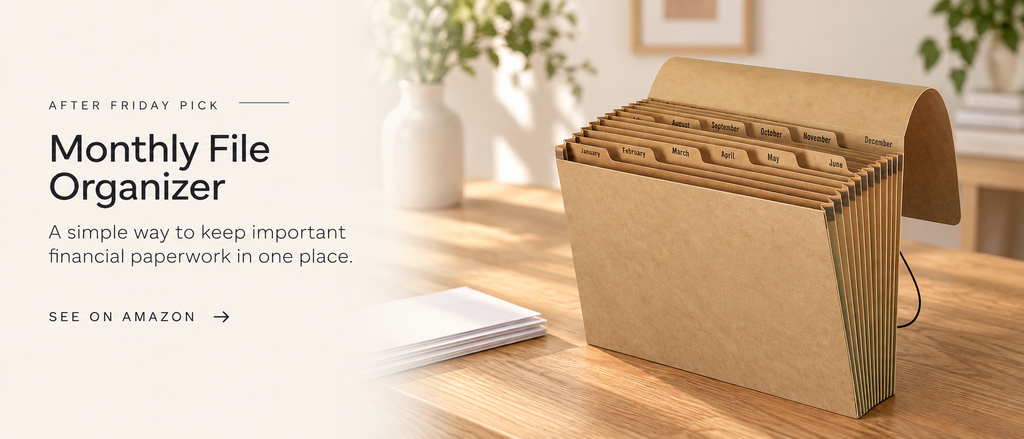
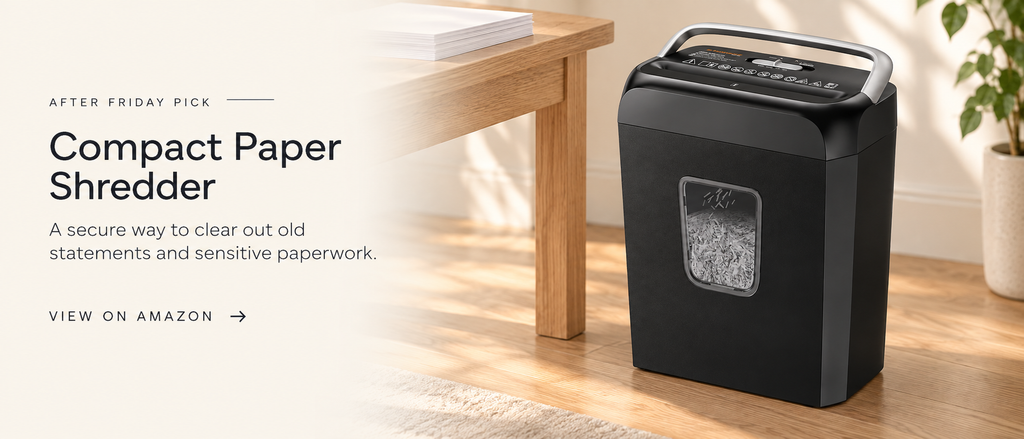
If you are sorting old paperwork, separate anything containing sensitive personal or financial information that should be securely destroyed rather than dropped into ordinary recycling.
If it has been a while, check your credit reports
This does not need to become a credit-repair project.
It is simply worth making sure the information being reported about you looks accurate.
Checking your own credit report does not hurt your credit score, and U.S. consumers can currently review reports from the three nationwide credit bureaus for free through the official AnnualCreditReport.com service.
If something needs disputing or further investigation, add it to your follow-up list.
You do not need to solve it before the afternoon ends.
3:45 PM — Write Down the Three Things Future-You Needs to Know
Before you close everything, create a very short handoff to yourself.
Write down:
One expense to expect
What is the next non-routine payment that could otherwise surprise you?
One action still open
Maybe:
“Call insurance Monday.”
“Compare phone plans.”
“Check credit report error.”
“Move $50 after payday.”
Specific beats “sort finances.”
Your next money check-in
Put 20 to 30 minutes on your calendar roughly a month from now.
That future check-in should be much smaller than today’s reset.
You will only need to:
- check balances
- scan recent transactions
- review upcoming bills
- look at subscriptions or renewals
- adjust anything that changed
- choose the next financial action
That is how the Saturday afternoon becomes useful beyond Saturday.
The Saturday Money Reset Checklist
If you want the whole afternoon in one place, save this:
- Write down your current checking and savings balances.
- Note credit cards, debt payments, and major upcoming expenses.
- Review the last month of spending for three patterns: surprising, recurring, adjustable.
- Audit subscriptions and recurring charges.
- Map the next 30 days of paydays, bills, renewals, and irregular expenses.
- Make one realistic adjustment to the month ahead.
- Set up one or two useful systems: savings, reminders, bill pay, or an expense fund.
- Organize important financial paperwork and note any follow-ups.
- Schedule your next 20-minute money check-in.
That is enough.
You do not need to end the afternoon with every debt strategy decided, every insurance policy compared, every account optimized, and the next twelve months perfectly forecast.
You need to know what is happening and what happens next.
What Not to Turn This Afternoon Into
A useful reset has boundaries.
If you uncover something significant — serious debt trouble, a tax problem, unfamiliar transactions, an insurance decision, an investment question, or a major credit-report issue — give that problem its own time.
Write down the next step.
Then finish today’s reset.
There will always be another account you could analyze or another spreadsheet you could improve.
The afternoon is done when your money no longer feels like one blurry unresolved task.
You know where you stand.
You know what is coming.
And you know the next thing to do.
Then close the laptop and have the rest of Saturday back.